Concentrated · Long-only · Global public equities
Maestria Partners invests for the long term in companies with competitive advantages and predictable cash flows.
A partnership that typically owns 10 to 15 high-quality businesses, researched from first principles and held for years, alongside a small group of aligned, long-term partners.
Investment philosophy
Enduring owners of a small number of exceptional businesses.
Maestria Partners is founded on the belief that concentrated portfolios of high-quality businesses with established competitive advantages and superior management can compound cash flows at high rates over long periods.
Our first-principles approach rests on a simple premise: cash-flow generation determines the value of a business, and the equity market reflects that value over time. We view each holding as a partnership with a high-integrity management team that has demonstrated operational ability and aligned capital-allocation priorities, and we draw on our long duration, an opportunistic approach, and deep primary research to invest when intrinsic value sits well above the market price.
We stay within our circle of competence, in predictable businesses facing low levels of technological and competitive disruption. The result is a concentrated portfolio of liquid, high-quality securities that should be expected to lag the market in speculative environments.
Five foundational beliefs
Some battles have already been won
Durable competitive advantages create the opportunity for persistent differential returns. Invest in predictable businesses that have already won. Fight unfair fights.
Markets are inefficient
Behavioral biases and human psychology change investor duration and priorities. People fail to understand non-linearity and extrapolate current conditions.
Volatility is not risk
Volatility moves market values. Free cash flow determines intrinsic value. Periods of heightened volatility create opportunities to invest in businesses at more favorable prices; the same volatility can also bring large and sustained drawdowns in the value of the portfolio.
Primary research is irreplicable
Investors who perform original and differentiated research better understand business fundamentals, market structures, and the nuances of competitive advantage.
360° alignment works; duration and partners matter
Expected returns are dynamic. Managing the portfolio for risk and expected return in a transparent, liquid partnership with fees built to align manager and partners creates understanding and builds trust.
Please see the fund offering documents for information on fees.
Investment criteria
Six criteria, assessed in sequence.
The first three describe the business. The fourth and fifth describe management and capital allocation. The sixth is valuation. Together, we believe they let us hold positions for long periods with low turnover.
- The business
Competitively advantaged business
A dominant business or market-share taker with pricing power and a high return on incremental invested capital, or little need to reinvest at all.
- The business
Large and growing addressable market
A runway that supports strong growth for at least the next five years, and ideally for decades, extending beyond any realistic forecasting period.
- The business
Predictable cash-flow growth algorithm
Growth at two or more times the rate of the underlying market, with subscription-like characteristics, so the business can be modeled with confidence.
- Management
Aligned management
Ethical, capable, aligned, and passionate operators who invest personally in the company and build a culture of frugal innovation and customer focus.
- Capital allocation
Expansion and incubation
The ability to grow beyond the current domain and incubate new products or services by leveraging existing advantages.
- The price
Valuation
An attractive five-year expected return with little or no leverage and a favorable balance of risk and reward, built from ten-year cash-flow models and anchored on the cash-flow multiple the business should command five years out.
How we assess competitive advantage
We use Hamilton Helmer's 7 Powers framework, breaking listed companies into their component businesses and assessing each business line separately. A competitive advantage exists if it allows a business to generate increased free cash flow that is material and immune to competitive pressures.
- Scale economies
- Network economies
- Counter-positioning
- Switching costs
- Branding
- Process power
- Cornered resource
Investment process
A library built over years, so we are ready when the market offers the right price.
Competitively advantaged businesses are rare and seldom undervalued. Because they are built slowly by good management teams, we can observe how each business and its market evolve, and wait for the inevitable but usually short intervals when a high-quality business trades below our observed estimate of intrinsic value.
The public equity universe holds more than 40,000 listed companies. Over 99% fall outside our focus. Our largest filters are illiquidity, the absence of a competitive advantage, an unpredictable business model, and weak management. Businesses valued below $500 million are too small for us to enter and exit without a meaningful market impact. We do, however, map private companies as competitors and as candidates for the Library, since private markets have sheltered many world-class businesses from public listing.
The too-hard pile
- Opaque financials
- Technically complex businesses
- Commodity businesses
- Pre-revenue companies
- Highly leveraged balance sheets
- Economically sensitive, unpredictable business models
- Companies not earning their cost of capital
- Companies not growing faster than their market
- Weak or declining unit economics
- High capital investment with uncertain recovery periods
- Level 1
The Maestria Library
Initial research on competitively advantaged businesses: a large knowledge base and set of contacts to build on when assessing a business model's strengths, weaknesses, and probable outcomes.
- Cloud services
- AI infrastructure
- E-commerce
- Service marketplaces
- Payment processors
- Alternative asset managers
- Railroads
- Aerospace
- Defense
- Financial exchanges
- Monopolies & oligopolies
- Diagnostics & medical devices
- Testing businesses
- Software
- Branded consumer goods
- Multi-unit consumer businesses
- Level 2
Active monitoring
Market maps and profit-pool analysis to understand how differential returns are earned over time. We engage with companies, expert networks, competitors, and current and former employees, focusing on drivers of market-share change, unit economics, and the evolution of business trends.
- Level 3
Primary research for inclusion
A written memo and detailed financial model documenting the durability of the competitive advantage, a refined thesis, a pre-mortem, and an assessment of risk factors and portfolio considerations. Valuation is usually the impediment at this stage.
- Level 4
Active monitoring and quarterly formal review
Each quarter's results are checked against the thesis, and we reassess the durability of the advantage and competitors' results for changing market dynamics. Models and expectations are updated relative to competing opportunities. We expect 1 to 4 new businesses to enter the portfolio in a typical year.
Portfolio
Concentrated, unlevered, and built to be resilient over long periods.
Positions are sized on the skew and distribution of expected return over the next five years, and the portfolio is managed to diversify sources of return, business model, sector, and duration. We expect short-term volatility, and returns that deviate significantly from the market over short and intermediate periods.
How we think about sources of return · Simplified example
Cash-flow growth
Revenue growth plus margin expansion.
Return of capital
Dividends and share repurchases.
Multiple expansion or contraction
We prefer businesses that become stronger over time through network effects, scale, switching costs, and brand. We believe such businesses will command higher multiples in the future.
New cash-flow streams
Internally incubated businesses, acquisitions, and expansion beyond the current domain.
Targeted five-year annualized return
Risk discipline
Years spent studying and partnering with investors, first as an endowment allocator, taught us that there is no single strategy for success. The one trait every long-term master shares is risk management.
Capital markets cannot be predicted, and as humans we carry psychological and behavioral biases. Investors therefore need a strong grasp of their own strategy and process, and conviction in their research, so the playbook is understood in advance of a drawdown rather than improvised during one. Our guidelines are managed at the level of each position and of the partnership's structure; they are disciplines, not mechanical limits.
Founder
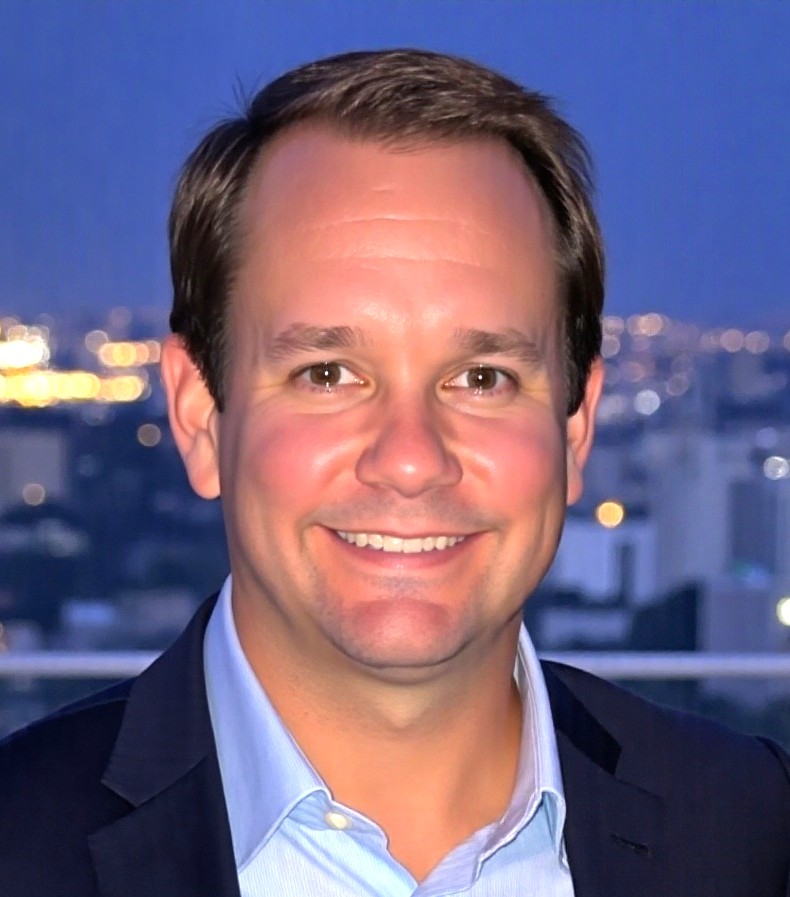
James Edwards
Founder & Managing Partner
James founded Maestria Partners in 2023 after eleven years investing on behalf of the UCLA and Emory University endowments, where he worked alongside investors, served as an allocator, and oversaw a portfolio of direct investments. That experience shaped a clear preference for concentrated, long-duration ownership of high-quality businesses, and refined the research and portfolio-management approach Maestria uses today.
He began investing at age ten after reading One Up on Wall Street. After college he briefly entered a financial-advisor training program, saw firsthand the agency problems of expensive and often poor-performing investment products, and returned to school for a master's degree in accounting. Six years at PwC followed, but the desire to invest professionally led him to the UCLA MBA program, where he specialized in investment management, was a Student Investment Fund Fellow, and worked as an analyst at a long/short equity hedge fund.
Maestria is a definitive step along a career devoted to the pursuit of mastery in investing. James invests his own capital alongside partners in a single strategy.
- Emory UniversitySenior Managing Director of Investments and Portfolio Manager of Equities, Emory Investment Management, 2018–2023
- UCLAInvestment Director, UCLA Investment Company, 2012–2018
- PwCConsulting engagements for global technology, media, and telecommunications clients, 2005–2010
- EducationBachelor's degree in Public Finance and master's degree in Accounting, Indiana University; MBA, Anderson School of Management at UCLA
- CredentialsCFA, CAIA, CPA (inactive)
How the firm is built
Maestria manages a single strategy, so no other business interests compete for the portfolio manager's time. There is one portfolio manager, and there always will be; the portfolio manager is involved in the analysis and primary research for every position.
Lack of focus, waning passion, a portfolio manager removed from research, leverage, over-concentration, and misaligned incentives are among the reasons successful investment organizations have failed. The partnership manages risk at the firm, strategy, and position level so that it is built for resilience and duration.
Partners and contact
We treat you as we would want to be treated.
Maestria manages a single strategy for a small group of like-minded partners with a five-year horizon, kept small so that every partner has direct access to the portfolio manager. We share holdings monthly, state the portfolio's five-year expected return every quarter so partners can make their own allocation decisions, discuss mistakes openly, and seek formal feedback each year. Two commitments govern the relationship.
Duty to serve
We treat all partners equally and honestly. We share our holdings and expected returns, discuss our mistakes transparently, and seek formal feedback from partners every year.
Duty to perform
If we cannot find investments that offer adequate returns, or cannot outperform the market over a prolonged period, we will return capital to our partners.
Existing and Potential Investors
Maestria does not solicit investors through this website. Interests in the partnership are offered privately, only to persons who qualify under applicable law and with whom the firm has an established relationship, and only through the fund's offering documents. If you have already been introduced to Maestria and would like to continue that conversation, please write to us.
Existing partners receive monthly holdings and performance reports, and a quarterly letter with attribution, portfolio changes, and the thesis behind each new investment, directly from Maestria. Monthly capital statements, annual audited financial statements, and Schedule K-1s are delivered through the fund administrator, HC Global Fund Services. Past letters and foundational materials are available on the Letters and Materials page to readers who register and are approved by Maestria.
Email info@maestriapartners.com